Publish Date: 22-09-2026
Auto Insurance
Does Car Insurance Cover Rust Damage?
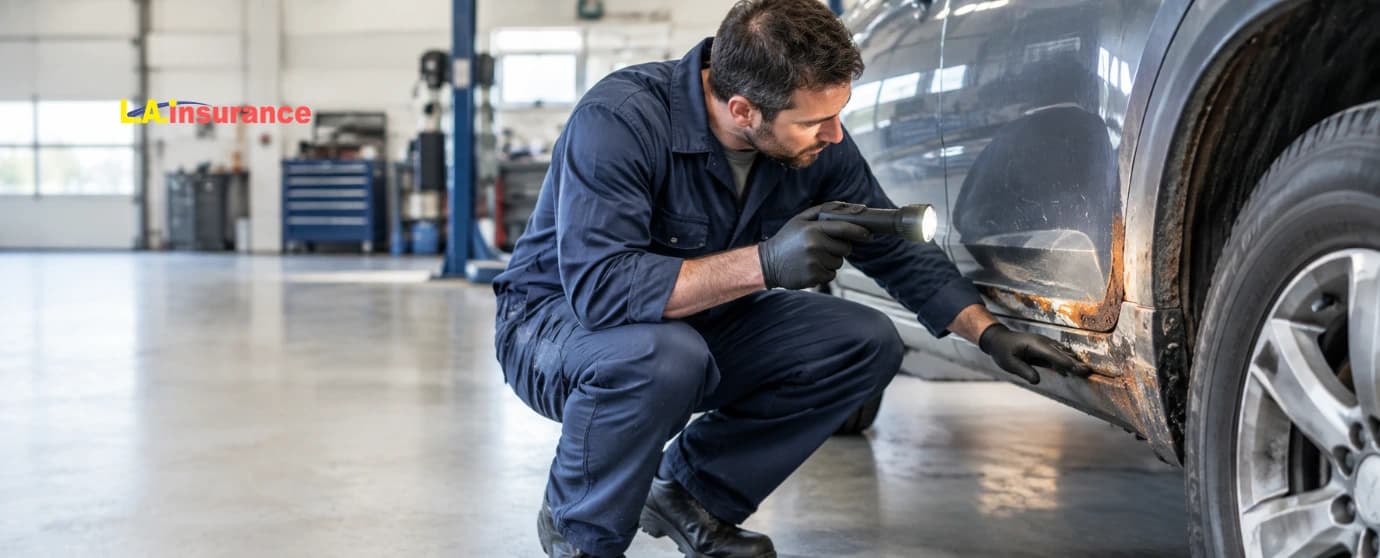
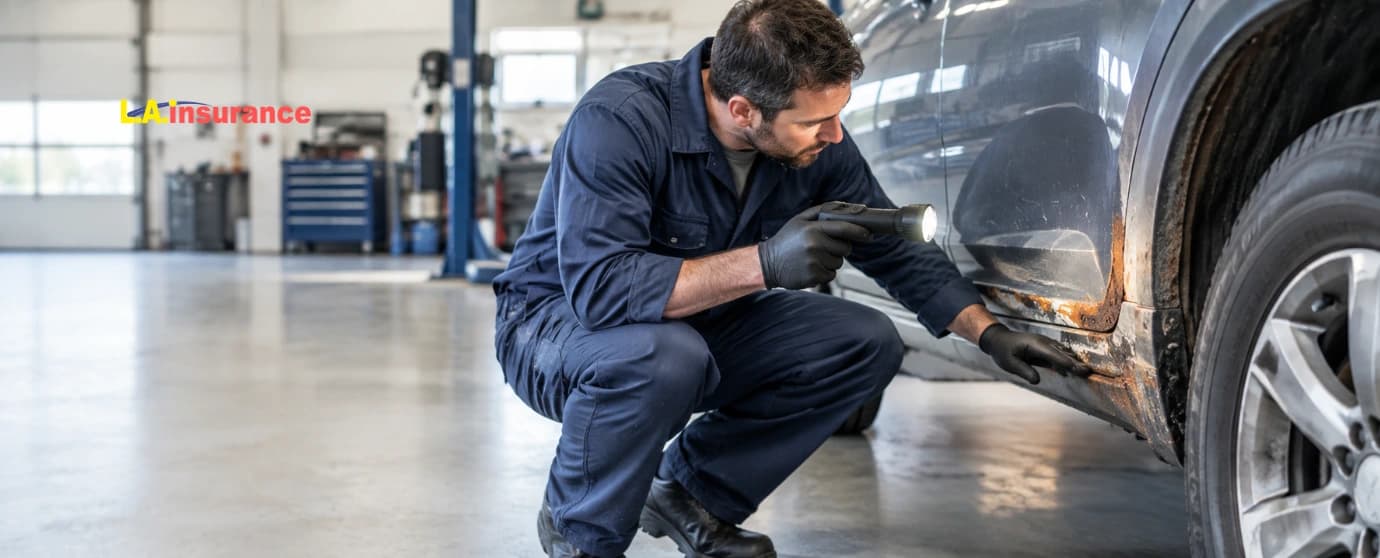
Rust can damage many parts of your car and may become more severe over time if left untreated. The undercarriage and frame components are particularly vulnerable to corrosion because they are regularly exposed to road salt, standing water, and debris. Other areas, such as the edges and hinges of the hood and trunk, can also develop rust.
So, if your car gets damaged by rust, will your car insurance cover it? Unfortunately, car insurance generally doesn’t cover rust damage. Insurers typically consider rust a form of gradual wear and tear or deterioration rather than sudden, accidental damage. However, coverage may apply in some situations when rust or corrosion results from a covered event.
In this guide, you’ll learn when car insurance may or may not cover rust damage, whether comprehensive and collision coverage apply, what you should do if your car develops rust, and how much rust repairs may cost.
Why Doesn’t Car Insurance Generally Cover Rust Damage?
Car insurance is designed to protect you against sudden and unexpected damage rather than problems that develop gradually over time. Rust typically falls into the latter category, which is why insurers generally exclude it from coverage.
When it comes to rust damage, it generally falls under common policy exclusions, which include the following.
Gradual Wear and Tear
Rust is generally considered a form of gradual wear and tear because it develops slowly rather than from a single, sudden incident. Your car’s exposure to moisture, humidity, road salt, and other corrosive elements can cause the metal to deteriorate over time.
- Initial Surface Rust: Surface rust can begin forming within a few days to several weeks after bare metal is exposed to moisture. It typically appears as small orange or reddish-brown spots on the metal surface and may be easier to remove or treat at this stage.
- Visible Pitting and Scale Rust: If surface rust is left untreated, it can progress to pitting and scale rust over several months to a few years. The corrosion begins penetrating deeper into the metal, creating rough, flaky, or uneven areas that can require more extensive repairs.
- Deep Penetrating Rust (Structural Damage): Severe rust can eventually penetrate deeply into metal components over several years (typically 3 to 10 years or more), although this can happen faster when your car is regularly exposed to moisture or road salt. At this stage, corrosion can affect critical components, including the vehicle frame, suspension components, brake lines, exhaust system, engine components, HVAC components, and electrical connections.
Since rust typically develops gradually and can often be prevented or addressed through regular maintenance, insurers generally classify it as wear and tear rather than sudden, accidental damage. As a result, standard car insurance typically doesn’t cover the cost of repairing rust that develops over time.
Negligence Due to Lack of Maintenance
Regular maintenance can help prevent minor rust from developing into more serious corrosion. If rust is left untreated for an extended period, it can spread and cause more extensive damage to your car’s body and components. Insurers may consider this a maintenance-related issue rather than an unexpected event, which means your policy typically won’t cover the resulting repair costs.
For example, failing to wash your car regularly, allowing road salt or moisture to remain on the metal, or ignoring small areas of surface rust can accelerate corrosion. Addressing these issues early and following your vehicle manufacturer’s recommended maintenance schedule can help prevent more severe rust damage and keep your car in better condition.
Road Salt and Corrosion
During winter, road crews often apply salt to roads to help melt ice and snow and improve driving conditions. As you drive over these treated roads, salty water and residue can splash onto your car, particularly its undercarriage, wheel wells, brake components, and other areas close to the road. The salt can also accumulate on your vehicle when you drive through slush or wet roads after a snowfall.
When road salt mixes with moisture, it can accelerate the corrosion of exposed metal. Repeated exposure can gradually wear away protective coatings and allow corrosion to spread deeper into the metal. If the buildup isn't washed away regularly, this process can eventually contribute to significant rust damage.
Since road salt causes corrosion gradually rather than through a sudden, accidental event, rust resulting from repeated exposure to road salt generally isn't covered by standard car insurance.
When Can Car Insurance Cover Rust-Related Damage?
Although standard car insurance generally doesn’t cover rust that develops gradually, there may be situations where corrosion or rust-related damage results from a covered event. In these cases, the cause of the damage is important in determining whether your auto insurance policy provides coverage.
As rust mainly happens due to weather conditions and environmental factors, comprehensive coverage may help pay for eligible rust-related damage resulting from certain incidents. Here are some common situations when your car insurance may cover rust damage.
Flood, Storms, Snow, and Other Weather-Related Risks
Severe weather can expose your car to water, moisture, debris, and other conditions that may cause corrosion or damage to metal components. Natural disasters such as flooding, hurricanes, snow, and hail can all contribute to rust-related problems, particularly when water reaches areas that are difficult to dry or clean.
If a covered weather event directly damages your vehicle, comprehensive insurance may help pay for the resulting damage, subject to your policy’s terms and deductible. For example, comprehensive coverage may cover damage caused by floodwater, falling objects during a storm, or other covered weather-related incidents.
However, comprehensive insurance generally does not cover rust that develops gradually from repeated exposure to moisture, snow, or other environmental conditions. The insurer will typically consider what caused the damage and whether it resulted directly from a covered event when evaluating your claim.
Damage From an Accident
An accident can damage your car’s body and expose bare metal to moisture, which may eventually lead to rust. For example, a collision that damages the paint, bumper, fender, or other body panels can leave the underlying metal vulnerable to corrosion if the damage is not repaired promptly.
If you have collision coverage, it may help pay for repairs to damage caused by a covered accident. However, collision insurance generally does not cover rust that develops later as a result of the unrepaired damage. Your insurer may also determine coverage based on whether the rust is directly related to the original accident or developed from prolonged exposure and lack of maintenance.
What Should You Do if Your Car Has Rust Damage?
If you notice rust on your car, addressing it early can help prevent the corrosion from spreading and causing more extensive damage. The steps you take may depend on how severe the rust is and whether it resulted from a covered incident.
- Inspect the damage: Check how far the rust has spread and whether it has affected important components or structural areas of the vehicle.
- Document the damage: Take clear photos of the rust and any underlying damage, especially if it may have resulted from a covered event.
- Have the rust assessed: A qualified auto body or repair professional can determine the severity of the corrosion and recommend the appropriate repairs.
- Check your insurance policy: Review your policy or contact your insurer to determine whether the damage may be covered. If the rust resulted from a recent covered incident, avoid making repairs before your insurer has had an opportunity to inspect the vehicle.
- Repair the rust promptly: Treating minor surface rust early can help prevent it from progressing into deeper corrosion that may require more expensive repairs.
If your insurer determines that the rust is related to gradual wear, environmental exposure, or lack of maintenance, you will generally need to pay for the repairs yourself. Even when rust-related damage is covered, consider your deductible before filing a claim. If the repair cost is close to or lower than your deductible, paying for the repairs yourself may make more financial sense.
For example, if your repair costs $700 and your comprehensive deductible is $500, your insurer would generally pay only the amount above your deductible. In this case, you may decide that filing a claim is not worthwhile since you would receive only $200 from your insurer after paying the $500 deductible. Additionally, filing a claim may affect your future insurance rates, depending on your insurer and policy.
Can Car Insurance Premiums Increase Due to Rust Damage?
Generally, car insurance premiums are not likely to increase simply because your car has surface or spot rust. If you pay for the repairs yourself and do not file an insurance claim, the rust itself typically will not affect your premiums.
However, if you file a claim for rust-related damage that is covered by your policy, your insurer may consider the claim when determining your future premiums. Severe rust can take a long time to develop, and if the damage is determined to be related to poor maintenance or gradual deterioration, it may not be covered in the first place.
So, before filing a claim, consider the repair cost, your deductible, and whether the potential payout is large enough to justify making a claim.
How Much Does It Cost to Repair Rust Damage on a Car?
The repair costs of fixing rust damage actually depend on the severity of the rust and the damage it has caused. According to auto repair shops like New England Rust Defenders, it can cost $50 to $200 to fix surface rust, while scale rust may cost $200 to $1,000, and structural or frame rust can cost $1,200 to $4,000 or more.
If you own a classic or luxury car, rust repair can cost much more, especially when it requires specialized restoration work. Based on repair estimates from The Restoration Sector, light rust repairs may cost around $2,600 to $10,400, while heavy rust repairs can exceed $32,000 and may reach $78,000 or more.
How to Prevent Rust Damage to Your Car?
Preventing rust is generally easier and less expensive than repairing extensive corrosion. While you cannot completely eliminate your car’s exposure to moisture and other corrosive elements, you can take several steps to reduce the risk of rust damage.
- Wash your car regularly: Clean your vehicle regularly to remove dirt, moisture, road salt, and other substances that can accelerate corrosion. Make sure to pay particular attention to the undercarriage and wheel wells.
- Remove road salt quickly: If you drive on salted roads during winter, wash your car as soon as practical to prevent salt residue from remaining on metal surfaces and accelerating corrosion.
- Keep your car dry: Avoid leaving your vehicle exposed to standing water or excessive moisture for extended periods. If your car gets wet, allowing it to dry thoroughly can help reduce prolonged moisture exposure.
- Repair paint damage promptly: Cosmetic or paint damage, such as chips, scratches, and dents can expose the underlying metal to moisture and oxygen. Repairing these areas early can help prevent surface rust from developing.
- Inspect your car regularly: Check the body, undercarriage, wheel wells, and other vulnerable areas for early signs of rust. Finding and treating small areas of corrosion before they spread can help prevent more expensive repairs.
- Apply protective treatments: Depending on your vehicle and climate, rustproofing or corrosion-resistant coatings may provide additional protection for vulnerable metal components.
The Bottom Line: Can You Rely on Auto Insurance to Cover Rust Damage?
Unfortunately, you can’t simply rely on auto insurance to cover rust that develops gradually from moisture, road salt, environmental exposure, or lack of maintenance. Insurers typically consider this type of corrosion to be wear and tear rather than sudden, accidental damage.
However, comprehensive or collision coverage may help pay for damage when a covered event, such as a flood, storm, or accident, causes the damage. Whether your policy covers the loss depends on the cause of the damage and the terms of your policy.
So, while your car insurance does not guarantee coverage for rust damage, there’s still a possibility of being covered, especially if it’s due to a covered incident. And that’s why it’s crucial to ensure you have the right coverage, especially comprehensive and collision coverage.
If you need help choosing the right car insurance policy with suitable coverage options, it may help to compare multiple insurers through an insurance agency. With over 34 years of experience, you can rely on L.A. Insurance to help you find coverage that fits your needs. If you’re ready to explore your options, get started with a free quote or connect with a nearby agent for expert advice.
Frequently Asked Questions (FAQs)
Does comprehensive insurance cover rust damage?
Comprehensive insurance generally does not cover rust that develops gradually. However, it may cover damage caused by a covered event, such as flooding or a severe storm, depending on your policy.
Does collision insurance cover rust damage?
Collision insurance generally does not cover rust itself. It may cover accident-related damage that exposes metal to moisture, but coverage for rust that develops later depends on the policy and circumstances.
Does full coverage car insurance cover rust?
Full coverage generally refers to having liability, comprehensive, and collision coverage. Even with these coverages, gradual rust is typically not covered, although damage from certain covered events may be.
Will car insurance cover rust caused by road salt?
Generally, no. Rust caused by repeated exposure to road salt is typically considered gradual corrosion or wear and tear rather than sudden damage.
Can I file an insurance claim for rust damage?
You can file a claim if you believe the rust-related damage resulted from a covered event. Your insurer will review the cause of the damage and your policy terms to determine whether it is covered.
Should you file an insurance claim for rust damage?
If the repair cost is close to your deductible, filing a claim may not be worthwhile. If the rust-related damage resulted from a covered incident, contact your insurer to determine whether filing a claim makes sense.
Editorial Disclaimer
The resources on this blog are researched and created by experienced insurance writers, then fact-checked and verified for accuracy to provide clear, general informational guidance. This content does not constitute professional insurance, legal, or financial advice. Coverage options and premium rates are subject to individual eligibility, underwriting guidelines, and state availability. For specific questions regarding your policy or to get an accurate quote, please contact a licensed L.A. Insurance agent directly. We're an independent agency and not a direct insurance carrier. For more information on how we operate and handle your data, please see our Terms and Conditions and Privacy Policy.
Tag :
Auto insurance
Comercial Auto
cheap car insurance
Does Car Insurance Cover Rust Damage?
Rust can damage many parts of your car and may become more severe over time if left untreated.
Does Insurance Cover a Tree Falling on Your Car?
Whether your car is parked out in the open under or near a tree, or you’re driving when a tree suddenly falls on your car, either way, it can leave your car severely damaged or even wrecked.
Does Car Insurance Cover Snow Damage?
Your car is more susceptible to damage in winter when it snows. As long as it’s out in the open, it can get damaged by snow at any moment.
Does Auto Insurance Cover Pets in the Car?
Whether you regularly drive with your pets in the car or only take them along occasionally, it’s worth knowing whether your auto insurance covers them.
Do You Need Car Insurance to Cover Road Trips?
If you’re wondering whether your standard auto insurance covers road trips, the good news is that it typically does.
Mechanical Breakdown Insurance: What Is It, and How Does It Work?
One of the biggest risks of owning a car is sudden mechanical failure, and the worst part is it can happen at any time.